On this page
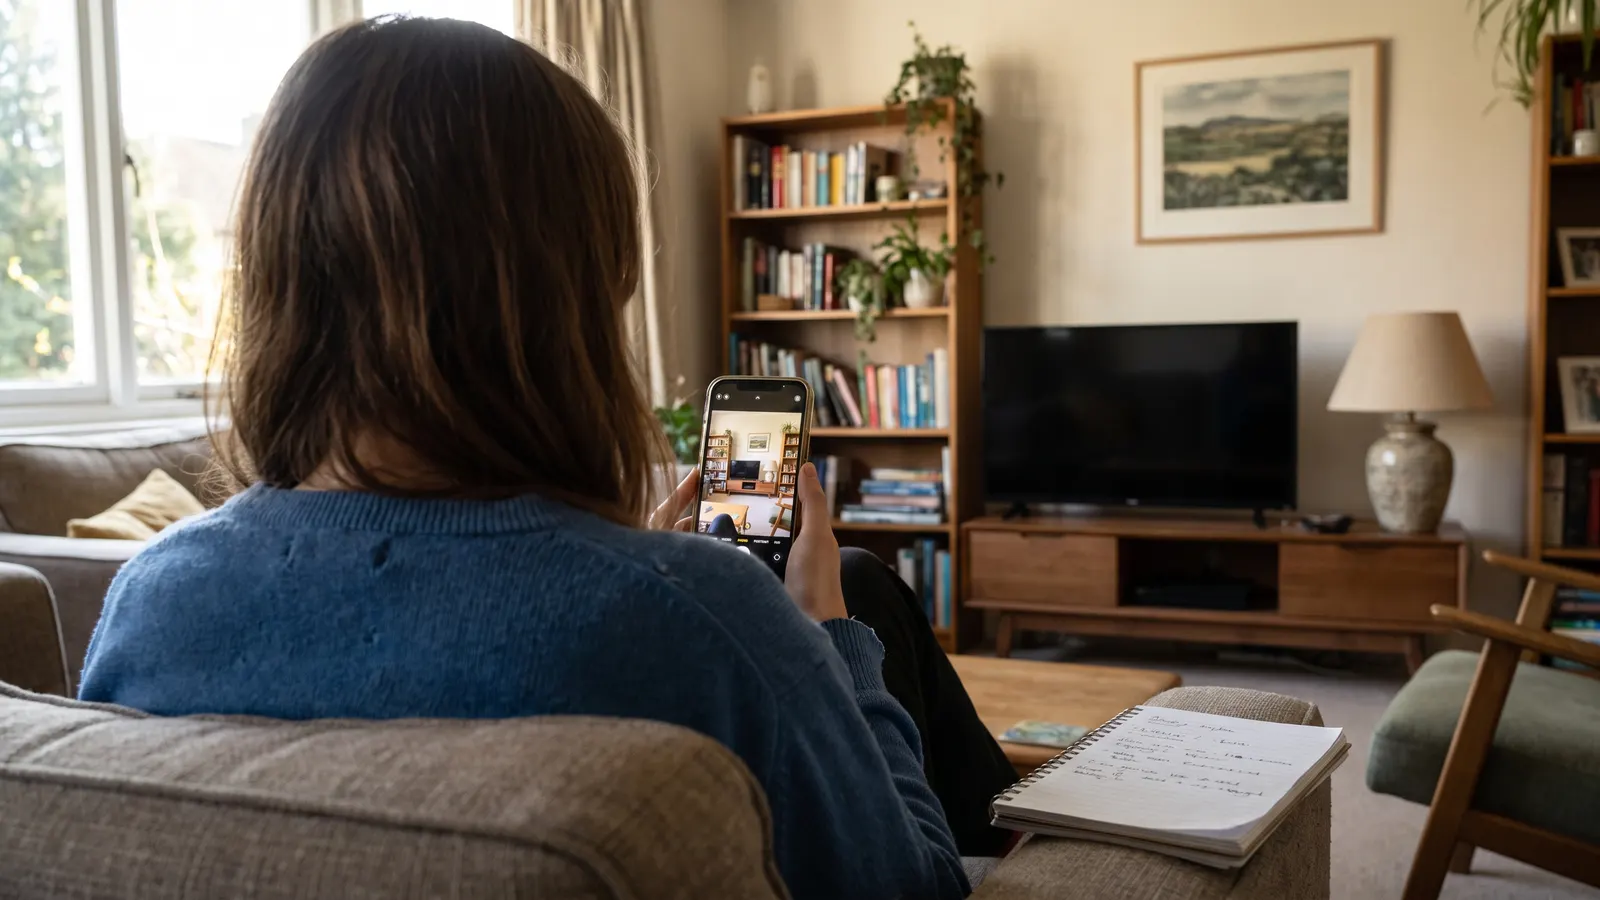
Build a home inventory one room at a time: stand in the doorway, take a video of the whole room with closets and drawers open, then list every item worth claiming with what it is, where you bought it, the make and model, the serial number, and what you paid. Attach the receipt or a photo of it. Store the finished list somewhere other than the house it describes. Done room by room, the whole job is an afternoon; done after a fire, it is a memory test with money on it.
The inventory belongs to the third part of a home record, what covers the house, next to the policy and the warranties. The closing-day documents are the other half of that folder.
Why does a home inventory matter?
A home inventory matters because a claim is settled on a list, and the list has to come from you. The Insurance Information Institute's guide to creating a home inventory gives three uses: it helps get a claim settled faster, it verifies losses for a tax return, and it tells you whether you are buying the right amount of insurance. The NAIC puts it more bluntly: an accurate inventory gives your carrier the information they need to settle your claim.
The failure mode is the same in every house without one. After a theft, a fire, or a flooded basement, the owner tries to remember what was in the room, cannot prove the television was the larger model, and cannot find the receipt for the camera. The adjuster is not being difficult; they have nothing to work from. A list with photos and prices, made before the loss, is the difference.
What should you record for each item?
Record, for each item, a description, where you bought it, the make and model, the serial number, and what you paid, which is the list the Insurance Information Institute gives. Add a photo of the item and, for anything with a receipt, a photo of the receipt. The institute notes that serial numbers are usually on the back or bottom of major appliances and electronics; a photo of the label is faster than typing it and cannot be mistyped.
| Field | Example | Where it comes from |
|---|---|---|
| Description | "Front-load washer, white" | You, standing in front of it |
| Where bought | The store or the site, and the year if you know it | The receipt, the order email, memory as a last resort |
| Make and model | Brand and the model number on the label | The label; the manual; the order confirmation |
| Serial number | The serial on the same label | Photograph it rather than typing it |
| Price paid | What it cost, including installation if that was part of the purchase | The receipt or the card statement |
| Photo | The item, and the label | Your phone, in the room |
Group items into categories or rooms, which is how the NAIC suggests organizing possessions, so the list can be read against a policy's coverage limits later. The serialized items in the kitchen and the laundry are also the appliance records the rest of the house record needs; organizing the manuals and serial numbers covers the same labels for a different purpose, and one photo serves both.
How do you work through the house room by room?
Work through the house in a fixed order, one room at a time, and finish each room before starting the next. The Insurance Information Institute suggests starting with a contained area, such as one closet or one cabinet, so the first session ends with something complete. Video each room first, then list the items that need detail, then move on. Do not try to list everything in the house on the first pass; get every room to "video plus the valuable items" and refine later.
- Stand in the doorwayVideo the whole room slowly, then open every closet, cabinet, and drawer on camera
- List the serialized itemsElectronics, appliances, tools, bikes, instruments: photograph each label
- List the valuable itemsFurniture, rugs, art, jewelry, collections, with a photo and the receipt or appraisal
- Note the built-insFixtures and finishes that a policy may treat as part of the house, so the line is clear
- Move to the next roomKitchen, living areas, bedrooms, closets, garage, basement, attic, outbuildings, in that order or any order you will finish
The garage, the basement, and the attic are where inventories fail, because nobody remembers what is stored there until it is gone. Video the shelves, open the bins, and photograph the tools and the sports equipment; they add up to more than most owners expect.
Which items need extra documentation?
Jewelry, art, and collectibles need more than a photo and a price, because a standard policy often limits what it pays for them and an insurer may ask for an appraisal. The Insurance Information Institute says these items may need separate coverage and that you should store receipts, contracts, and appraisals with the list. Ask your agent what your policy limits and what it needs from you; the policy is the only source for what it covers.
- Jewelry, watches, and collections: the receipt, an appraisal if you have one, and a photo that shows the item clearly
- Art and antiques: the receipt or the provenance you have, and a photo in place
- Electronics and cameras: the serial, the receipt, and the accessories bought with them
- Tools and equipment: the serial where there is one, and a photo of the set
- Anything you rebuilt or upgraded: the receipts for the parts, which a claim can otherwise miss
What counts as personal property, and what the policy treats as part of the building, varies by policy. Ask your agent where the line is for built-in appliances, fixtures, and outdoor equipment, and inventory both sides of it so you have the record whichever way the policy reads.
Where should the inventory live?
The inventory should live somewhere that survives the house: a copy outside the home, as the Insurance Information Institute says, in a safe deposit box or with a relative, and a digital copy in the cloud or on an external drive, which is where Ready.gov's financial preparedness page says to keep important documents so they are reachable during a disaster. A list stored only on the laptop in the house it describes is lost in the same event as the things it lists.
The NAIC offers a free Home Inventory app that captures photos grouped by room or category, scans barcodes, and exports the inventory at any time. Any tool that keeps the photo, the serial, and the receipt together and lets you export the list works; the export is what you hand to the adjuster.
In Property Station, Room Inventory under My Home holds the items by room with a Warranty Expiry per item, the receipts go in Documents (or through Scan Receipt, which reads a JPG, PNG, or WebP photo up to 10 MB and files it), and Data Export produces the Inventory as a CSV. The Document Vault is where the appraisals and the policy sit next to it. That CSV, with the photos and receipts, is the list an insurer asks for.
How do you keep it current?
Keep the inventory current by adding items and receipts while the details are fresh, which is the Insurance Information Institute's advice, and by walking the house once a year, at the same time you review the policy. Ready.gov's financial preparedness page also says to review insurance coverage against all possible hazards, and the inventory is what makes that review concrete: the total on the list is what the personal property coverage has to reach.
A new purchase takes a minute if you do it in the store parking lot: photograph the receipt, photograph the label when it is unboxed, add the item to its room. A renovation, a move, or an inheritance is a reason to redo the affected rooms rather than patch the list. The inventory is also the family's list, not only the insurer's; the home binder is where a summary of it sits so someone else can find it.
Common questions
Do I need to inventory everything I own?
No. Start with what would be expensive or hard to replace and with the items an adjuster would question, then fill in the rest over time. A room-level video plus a detailed list of the valuable and serialized items is a working inventory; a spreadsheet of every fork is not a better one.
Is a video walkthrough enough on its own?
It is a good start and better than nothing, because it proves what was in each room. It is weak on the details a claim needs, such as the model, the serial, and the price, so pair it with a written list for anything valuable or serialized, and keep the receipts with the list.
How often should I update the inventory?
Add items as you buy them, while the receipt is in your hand, and do a walk-through once a year, at the same time you review the insurance policy. A big purchase, a renovation, or a move is a reason to update it right away.
Where should I keep the inventory?
Somewhere that survives the house: a copy outside the home, in the cloud, on an external drive, or with a relative, and not only in a drawer in the house it describes. The Insurance Information Institute and Ready.gov both say the same thing about important documents.
What should you do next?
Pick the room with the most expensive things in it, usually the living room or the office, and inventory that one room tonight: the video, the labels, the receipts you can find. Then read what your policy covers for a new build or ask your agent what yours covers, and compare the total on the list to the personal property limit on the declarations page.